

Is the US Federal Reserve About to Hike?
September 14, 2026
 The US Federal Reserve hiked its policy rate by 0.25% last week, as expected.
In its very brief accompanying statement, the Fed assessed that “economic activity is expanding at a solid pace”, despite elevated geopolitical uncertainty. It observed “resilient” domestic spending, “strong” productivity growth, “robust” capital investment, and job gains that have “kept pace” with expansion of the workforce.
The only flaw in the Fed’s latest report on the economy was that “inflation remains elevated”. It justified its rate hike decision, which was unanimous, to “support a timelier return” to its 2% inflation target.
The Fed also released its latest dot plot chart, which shows each individual Fed official’s forecast for its policy rate (sans Fed Chair Kevin Warsh). The median Federal Open Market Committee (FOMC) participant now sees the Fed’s funds rate ending 2026 at 4.1%, up from 3.8% in June. With its current policy-rate range at 3.75%–4.00%, that presages one additional 0.25% hike this year.
The Fed’s policy-rate movements have implications for Canadian mortgage rates.
Fed rate hikes typically put upward pressure on US Treasury yields, and Government of Canada (GoC) bond yields, which our fixed mortgage rates are priced on, are highly correlated to their US Treasury equivalents. That means our fixed mortgage rates will tend to move in the same direction as US Treasury yields over time.
Interestingly, US Treasury yields may not increase further in this instance.
Bond-market investors had already pushed yields higher over concerns about elevated US inflation and in anticipation of the Fed’s hike. The upside risk to yields this time would have been more significant if the Fed hadn’t followed through.
The Fed’s most recent hike also expands the gap between the US/Canada policy rate. For reference, the Bank of Canada’s (BoC) policy rate currently stands at 2.25%.
A wider US/Canada policy-rate gap puts downward pressure on the Loonie. That adds inflation pressure because it increases the cost of everything we import from the US.
Canadian inflation is cooler than US inflation, but we face the same risk that spiking energy prices will lead to more generalized price rises. A weaker Loonie adds fuel to that fire.
The Latest on Mortgage Rates
GoC bond yields dropped a little last week alongside their US Treasury equivalents. This was a classic case of bond market investors buying the rumour (that the Fed would hike) and then selling the fact (when it did).
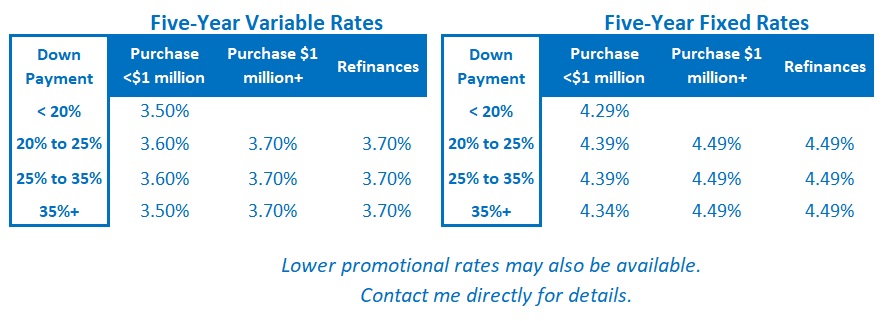
Canadian lenders continued to raise their fixed mortgage rates last week in response to the previous bond-yield run up. Over the near term, we should continue to expect those rates to follow where oil prices lead.
Variable mortgage-rate discounts held steady last week.
The Fed’s rate hike may increase the likelihood of a BoC rate hike later this year if the Loonie weakens materially (although it hasn’t moved much thus far).
Bond-market investors have priced in five 0.25% hikes by the BoC between now and the end of 2027.
I am still not convinced that BoC rate hikes will materialize in the quantity expected, but there is no denying the current upward momentum in bond yields and short-term rate hike expectations.
My Take on Today’s Mortgage Options
My take is unchanged from last week.
I can well appreciate the appeal of fixed-rate stability in our current volatile environment.
Many of the borrowers I work with today are choosing fixed rates, and I’m not trying to talk anyone out of those options. I see the value of certainty in an increasingly uncertain world, even if it comes at higher cost.
When asked for my view on whether a fixed or variable rate is more likely to prove cheaper, I maintain my view that today’s variable rates have the best chance to save borrowers money over their full terms – an admittedly contrarian call right now.
Variable mortgage rates have held steady, but the backdrop that is keeping them in place is anything but stable. Until recently, two competing risks had been roughly offsetting each other: 1) The upside risk that spiking energy prices will lead to generalized inflation, and 2) the downside risk that the US/Canada trade war will disrupt our economy and cause disinflation. A resurgence in the energy-price run up has already spooked global bond markets, and GoC bond yields are being taken along for the ride.
I still expect the disinflationary impacts from trade issues to last longer than the inflationary impacts from higher energy prices. But for now, higher energy prices are dominating the inflation narrative – and will continue to do so for as long as war rages in the Middle East.
Important note: Anyone choosing a variable rate should do so only if they are comfortable with its inherent potential for volatility. Borrowers must have the financial capacity to withstand higher costs and, in some cases, higher payments.
That said, it is also important to note that fixed rates come with risk. If bond yields rise sharply in anticipation of higher inflation that doesn’t ultimately materialize, anyone who locked in a fixed rate during the run-up will be paying that associated premium regardless of any subsequent yield/rate reductions
Insider’s Tip for Borrowers
If you’re in the market for a mortgage, instead of focusing on how much you can borrow, you will be far better off in the long run by focusing on how much you can (conservatively) afford to pay.
A lender doesn’t care if you ever save for retirement, take a vacation, or go out for a nice dinner. With that in mind, when you decide how much you will borrow, focus on what works for your budget, not on the maximum amount you can borrow.
This post offers advice on how to work out a reasonable mortgage budget using two different approaches: the easy way and the hard way.
Three Posts Every New Visitor to My Blog Should Read
This post provides a detailed comparison of the pros and cons of fixed- and variable-rate mortgages amidst trade-related economic uncertainty.
For myriad reasons, often unanticipated, many Canadians end up having to break their fixed-rate mortgages. This post provides a detailed explanation of the very different ways that lenders calculate their fixed-rate mortgage penalties. The amounts charged can vary significantly from lender to lender.
This post provides a detailed summary of the key terms and conditions to pay attention to in your mortgage contract. (These are not standard and can vary in important ways.)